Chapter 4 - The Bank's Inquiry
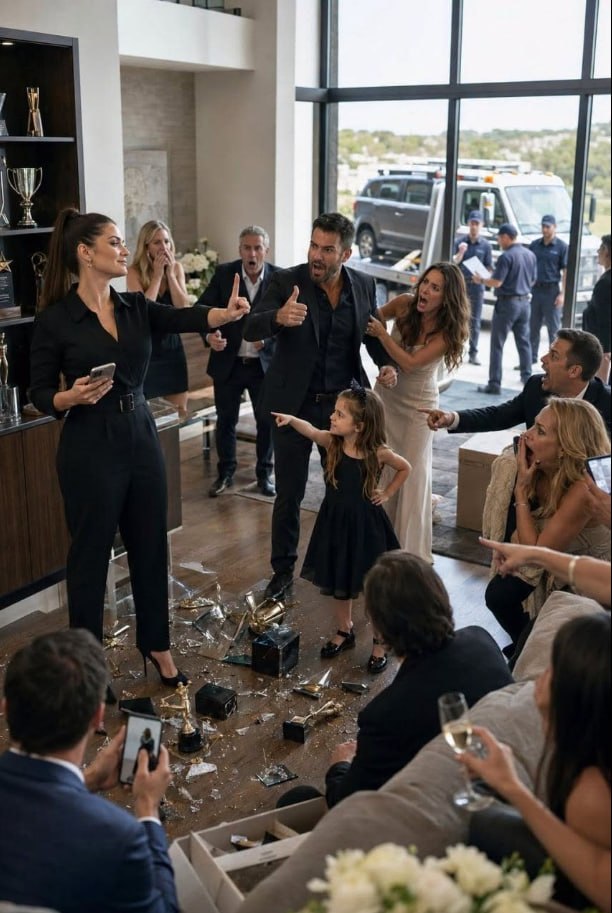
Two days passed without a word from Travis. His silence wasn't surprising—his pride was a towering, fragile monument built on years of family enabling. But while Travis was stewing in his anger, the financial infrastructure beneath him was beginning to crumble.
On Thursday morning, I received a call from Arthur Vance, a senior commercial loan officer at First National Bank. Arthur was an old acquaintance of my father and the man who had overseen the $150,000 line of credit for Crossroads Contracting.
"Lauren, good morning," Arthur’s deep, measured voice came through the line. "I hope I'm not interrupting your workday."
"Not at all, Arthur. What can I do for you?"
"I'm calling regarding the commercial credit facility for Crossroads Contracting LLC," Arthur said, rustling papers on his end. "As you know, you are the primary guarantor and cosigner on that loan account."
"I am well aware," I said.
"We received a automated system alert this morning," Arthur explained. "Crossroads Contracting’s business checking account missed its automated quarterly debt-service ratio audit. Furthermore, we noticed a sudden halt in their incoming digital merchant transactions over the last four days. Standard procedure requires us to contact the primary guarantor before initiating a formal credit review."
I took a quiet breath. This was the moment where the safety net I had provided for Travis would either hold or snap completely.
"Arthur," I said carefully. "As the cosigner, am I currently in default?"
"No, the account payments are current for this month," Arthur clarified. "However, under Clause 14 of the guarantor agreement, if the operating business experiences a catastrophic operational disruption that threatens its ability to service the debt, the guarantor has the right to request an immediate freeze on the credit line to protect themselves from liability."
"And what happens if I request that freeze?"
"We temporarily lock the remaining balance on the credit line—which currently sits at $45,000 in available capital—and demand an audited financial statement from Mr. Travis Cross within ten business days to prove solvency."
I looked out my office window at the old maple trees lining my quiet street. For three years, Travis had used that $45,000 safety cushion to buy materials upfront for jobs before getting paid by clients. If I froze that line, he wouldn't be able to buy lumber, pay concrete suppliers, or rent heavy machinery for his upcoming projects.
He would be completely paralyzed.
"Arthur," I said, my voice unwavering. "I would like to formally exercise my right under Clause 14. Freeze the credit line immediately."
There was a brief pause on the line. Arthur knew our family history. He knew I had backed Travis out of sibling loyalty.
"Are you sure, Lauren?" Arthur asked quietly. "This will severely restrict his operating ability."
"He destroyed my property, Arthur," I replied simply. "And he did it while claiming he built his business all by himself. It’s time for him to prove it."
"Understood," Arthur said. "The freeze will be active as of 12:00 PM today. A formal notice will be dispatched to Mr. Cross electronically and via certified mail."
Ten minutes after the call ended, my phone lit up with a text message from my father—the first time he had contacted me since the housewarming party.
Lauren, your mother told me what’s happening. You need to come to the house for dinner tonight. We need to settle this as a family before everything falls apart.
May you like
I replied with a single sentence:
I will be there at 6:00 PM. But I am not coming to negotiate.